
Financial paperwork has a remarkable ability to sound both urgent and unwilling to explain itself.
A tax code arrives as a string of numbers and letters, apparently confident that the two of you have met before. A pension statement talks about your retirement as though you’ve been planning it together for years. Credit scores hover in the background like an exam nobody remembers sitting.
Adult life contains a surprising amount of pretending that this all makes perfect sense.
I came to financial education later than I thought I should have. Whenever one of these subjects finally clicked, I tended to feel two things in quick succession: relief that I understood it, followed by irritation that the explanation had been so difficult to find.
That combination eventually became a book.
I didn’t want to write a book about getting rich
There are already plenty of books about building wealth, beating the market and transforming your finances before breakfast. This is not one of them.
I was more interested in the quieter layer underneath all of that: the knowledge you need before most conventional money advice becomes useful.
What does this line on a payslip mean? What actually happens when somebody checks your credit? Is a workplace pension the same thing as a private pension? What does becoming a guarantor make you responsible for? If two people share an account, whose money is it legally?
These are not glamorous questions. They are, however, the questions that can matter enormously on an otherwise ordinary Tuesday.
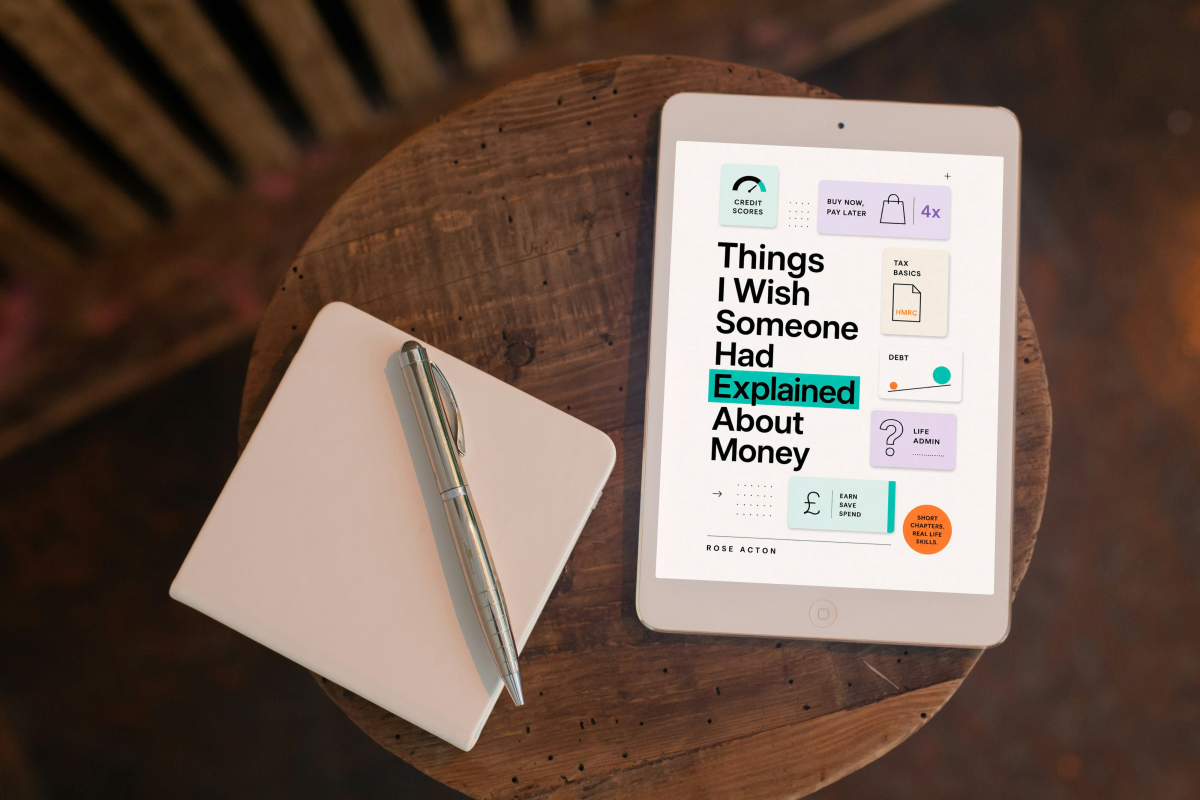
The book is called Things I Wish Someone Had Explained About Money because that is quite literally what it became: a collection of explanations I would have liked to receive before the relevant paperwork was sitting in front of me.
The chapters came from ordinary moments
The book contains 25 short chapters, but it isn’t intended to be a complete encyclopaedia of personal finance. It follows the subjects that tend to enter ordinary life without much ceremony.
There is the first payslip from a new job, with an unfamiliar tax code attached. The credit application that asks whether you understand the consequences of something nobody has yet explained. The pension contribution you know is probably important, although retirement feels too distant to picture properly.
Then there are the subjects that arrive when life becomes more serious: funeral costs, wills and life insurance. By the time you need to think about them, you are not usually in an ideal mood for a glossary.
And, inevitably, there is money involving other people. Joint accounts, moving in together, lending to family, guaranteeing somebody else’s borrowing and working out what happens to shared debts after a relationship ends. Financial systems often treat these as administrative arrangements. Human beings rarely experience them that way.
Writing the chapters made me notice how much of adult finance relies on implied knowledge. The forms explain what information they want from you. They are much less interested in explaining why it matters.
The book has one fairly specific job
I wanted the book to lower the temperature of those moments.
Not to provide a perfect answer for every reader or replace professional advice, but to help somebody understand what they are looking at before panic, embarrassment or frantic searching takes over.
That shaped the way it was written. The chapters are short. Technical language is translated as it appears. The recurring Quick version sections are there for the moment when you do not have the patience for a lengthy introduction. Tiny red flag points out details worth stopping over. Quick translation turns official wording back into something resembling a sentence a person might actually say.
I also tried to leave room for life as it is actually lived. Sometimes there is not enough money. Sometimes somebody is ill, grieving, exhausted or trapped in a difficult relationship. Sometimes the objectively sensible administrative task remains undone because opening the envelope is the most a person can manage that day.
A useful explanation should still work in those circumstances.
What I deliberately left out
There are no miracle systems in the book. No morning routine is presented as the final missing piece of your financial future. Nobody is asked to develop a passion for spreadsheets.
It also does not assume that every reader is aiming to become a particularly enthusiastic investor. Some people want to build significant wealth. Other people would simply like to understand why their take-home pay changed and whether the email from a debt collector can be ignored. Both deserve clear information.
The tone mattered to me for the same reason. Money is serious, but writing about it does not have to sound like a bank leaflet. It can be practical without becoming stern, and honest without turning every financial mistake into a moral lesson.
It is now an actual book
After the writing, editing, checking, formatting and repeated discovery that one small clarification creates three new questions, the book now exists beyond a folder on my computer.
That feels exciting, slightly strange and much more exposing than quietly publishing another blog post.
I hope it becomes the kind of book people keep rather than ceremonially “finish”: something to return to when a suspicious payslip, credit application, pension form or piece of serious life admin appears.
Things I Wish Someone Had Explained About Money by Rose Acton is available now as a Kindle ebook through Amazon UK.
Take a closer look at the book, or view it directly on Amazon UK.
The book provides general educational information and does not constitute personalised financial, investment, legal or tax advice. Rules and allowances can change, and individual circumstances differ.